No. Mortgage life insurance is optional in Canada. You do not need to buy it to be approved for a mortgage. It can be useful for some households, but the right question is whether this particular policy protects the people who depend on you in the way you want.
It is easy to confuse mortgage life insurance with mortgage default insurance. They sound alike, yet they solve different problems. Before you agree to either charge, ask what triggers a payment, who receives it, and whether the product is required.
What does mortgage life insurance do?
Mortgage life insurance may pay the outstanding mortgage balance to the lender if an insured borrower dies, subject to the policy terms and a valid claim. The lender receives the payment. Your family does not receive a separate cash benefit from that policy, although paying off the mortgage could reduce their housing costs.
The Financial Consumer Agency of Canada (FCAC) says this coverage is optional and is often offered when you take out or renew a mortgage. The premium is generally based on your age and the mortgage amount when you apply. As you pay the balance down, the amount the policy could pay also falls, while the premium generally stays the same. Read the actual certificate for the terms that apply to you.
If you have a spouse, children, or another person who could struggle to keep the home after your death, this is a reasonable risk to consider. It does not automatically mean lender-offered mortgage life insurance is the best way to cover it.
Is this the insurance required with a small down payment?
No. Mortgage default insurance is a different product. It protects the lender if the borrower defaults. In Canada, it is generally required when the down payment is less than 20% of the purchase price. It does not pay your family if you die and does not replace life insurance. Our mortgage default insurance guide explains the cost and purpose in more detail.
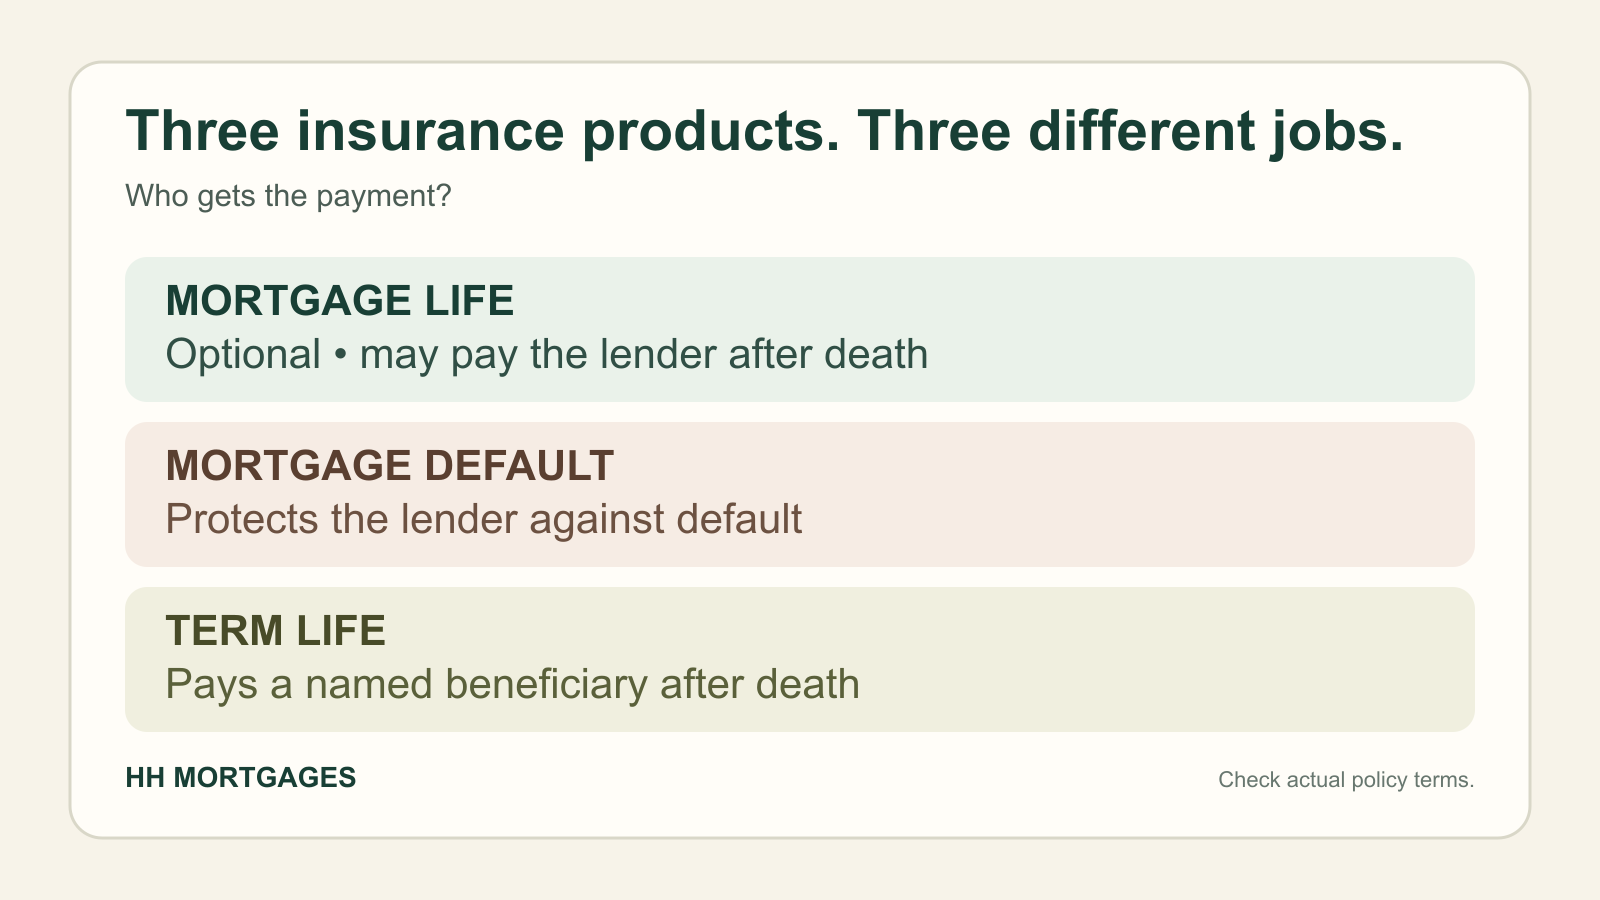
Here is the distinction to keep in mind:
- Mortgage life insurance: optional coverage that may pay the mortgage lender after an insured borrower's death, subject to the policy.
- Mortgage default insurance: lender protection against default, generally required for a purchase with less than 20% down.
- Individual term life insurance: coverage for a chosen period that pays a named beneficiary if the insured person dies while the policy is in force. The beneficiary can decide how to use the money.
This comparison describes the basic purpose of each product. Eligibility, exclusions, coverage limits, premiums, and claims all depend on the actual contract.
Mortgage life insurance or term life insurance?
An individual term life policy is another way to plan for a mortgage-sized risk. You choose a coverage amount and name a beneficiary. If the claim is payable, that person receives the death benefit and can decide whether to use it for the mortgage, living expenses, or another need. FCAC's life-insurance guide explains that term insurance covers a defined period and pays the named beneficiary if a claim is payable during that period.
That flexibility matters. A mortgage balance normally shrinks. A level-benefit term policy can keep the same death benefit while it is in force; mortgage life coverage is tied to the amount still owing. But do not assume one option is always cheaper or better. Premiums, medical questions, exclusions, renewal terms and eligibility can differ. Compare actual quotes and policy documents, not a slogan about either product.
First, check coverage you already have. Workplace group life insurance may help, but it may end when you leave the job. FCAC advises checking the conditions and comparing policies before you buy. Ask your benefits administrator what amount you have, when it ends, and whether a new personal policy would fill a real gap.
Five questions to ask before you sign
- What exactly is covered? Ask whether the certificate covers death only or includes separate disability or critical illness benefits. Check exclusions, age limits, claim conditions, and the amount payable.
- Who gets the money? With lender-offered mortgage life insurance, the benefit goes to the lender to pay the mortgage. With an individual life policy, the named beneficiary generally receives the benefit.
- What will I pay over time? Get the premium and payment frequency in writing. Ask whether the premium changes and compare it with the coverage remaining as the mortgage balance falls.
- What happens if my mortgage changes? Ask what happens at renewal, on a lender switch, after refinancing, or if you pay the mortgage off early. Do not assume coverage follows you unchanged.
- What coverage do I already have? Review personal and workplace policies before buying another one. Consider the needs of anyone who depends on your income, not just the mortgage balance.
If a federally regulated bank or federal credit union offers you this optional product, FCAC's consumer-rights guidance says the institution must explain charges, obtain your express consent, and give you an option to cancel. Ask for the disclosure and policy certificate before deciding. Rules for other providers can differ, so review their documents and ask a licensed insurance professional when the terms are unclear.
What I would focus on
I would separate the mortgage decision from the insurance decision. You can compare mortgage offers without treating an optional insurance checkbox as part of approval. Then you can look at the people who would need support, the coverage you already hold, and two or more policy options.
You do not need to make an insurance choice from a rushed conversation at the end of a mortgage application. If you are uncertain, ask a licensed life insurance agent to explain the policy and compare suitable coverage. For the mortgage itself, I can help you understand the lender's written terms and where an optional charge appears in the payment.
If you are reviewing a mortgage offer in Ontario, send me your mortgage questions. We can separate the required costs from the optional products before you decide.
General education only, not individual mortgage, legal, or insurance advice. Insurance approval, premiums, exclusions and claims depend on the policy and insurer. Speak with a licensed insurance professional about your protection needs. Hanif Hosseini, Mortgage Agent Level 1, M26001653. Mortgage Architects, brokerage licence #12728. Serving Ontario, based in Oakville.